Selling a Home on Sullivan's Island: When to Hold Your Price and When to Reprice
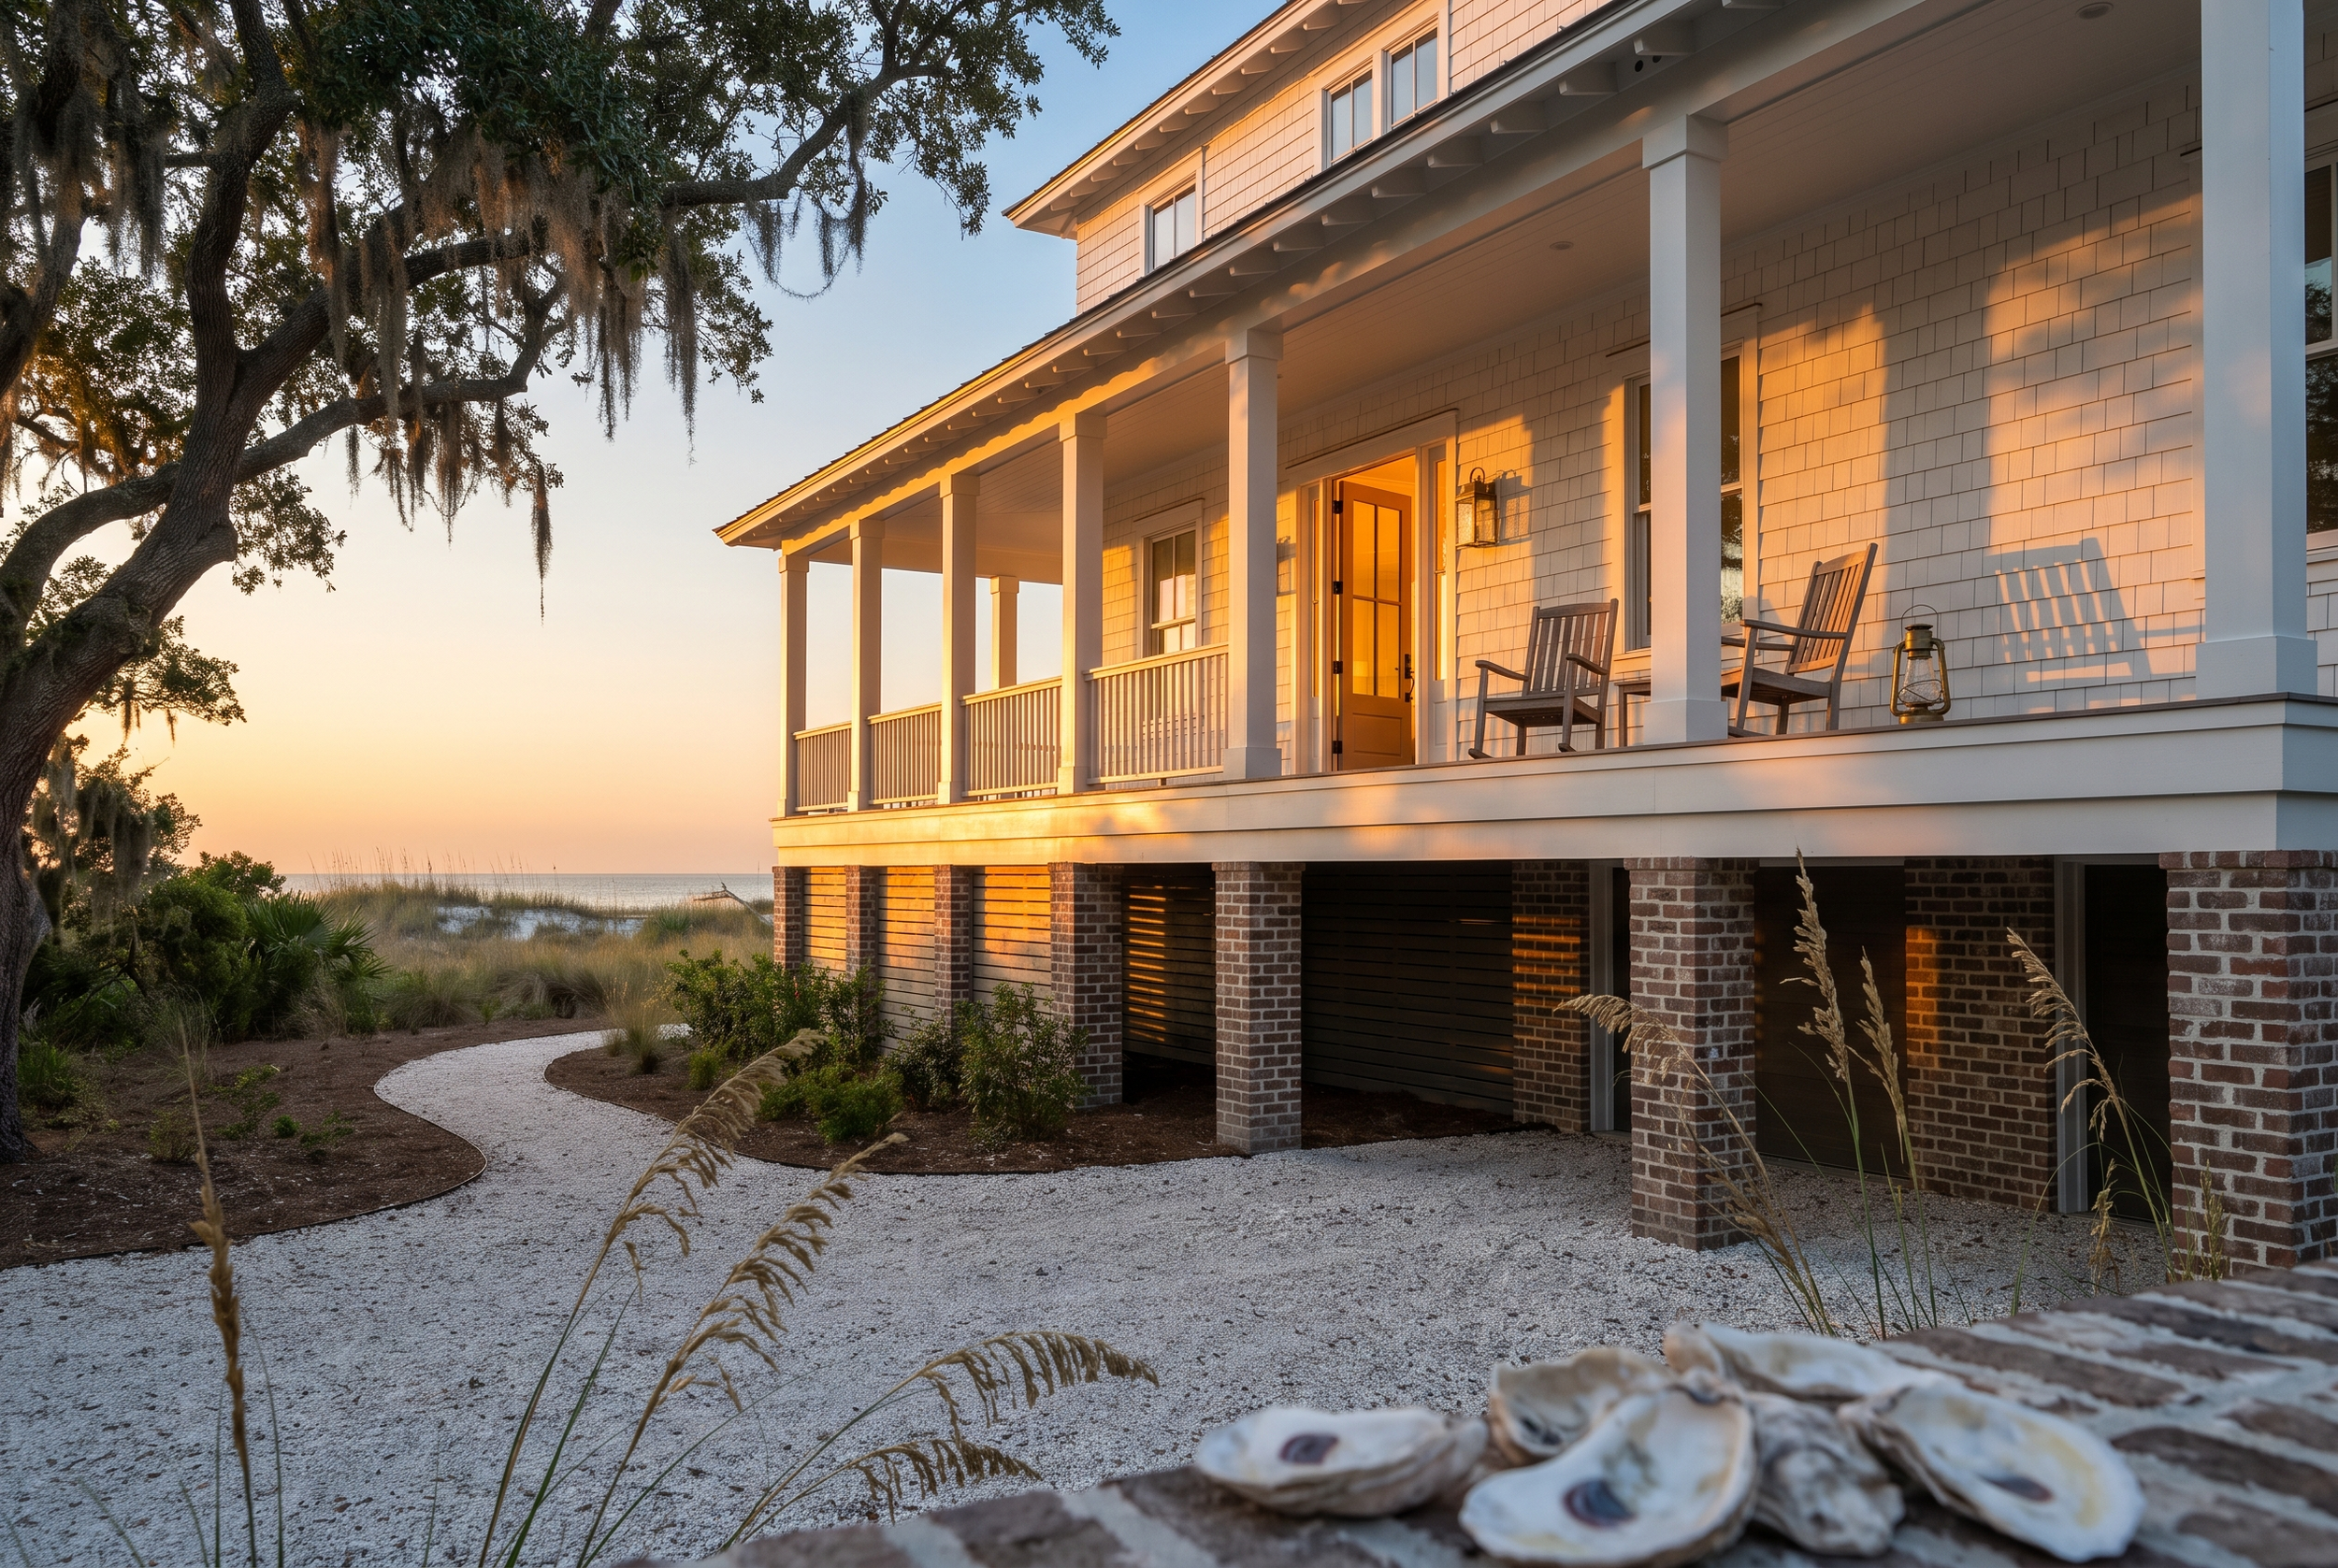
If your Sullivan's Island home has been listed three months without an offer, you are on schedule — not behind it. The median Sullivan's Island home that closed in August 2026 took 147 days, per Redfin, as of August 2026. Nearly five months. So a price cut is not automatically the fix: on a property you own free and clear, five more months of carry runs within a few thousand dollars of a 3% reduction. The decision turns on your leverage and the actual objection, not on patience. Here is the math.
Key Takeaways
147 days. Median days on market for Sullivan's Island, up 56 days year over year (Redfin, as of August 2026).
51 days. The comparable figure for the whole Charleston Trident region, at 95.8% of original list price received (per Charleston Trident Association of Realtors / ShowingTime, as of August 2026).
Rates moved against you this month. The 30-year fixed averaged 7.28% on October 1 (per Freddie Mac PMMS, October 2026), up from 7.03% a week earlier. Bankrate's October 7 lender survey put it at 7.53% — the highest since November 2023.
A 3% cut on a $3.6M home is about $108,000. On a low-leverage property, roughly five months of true carry costs about the same. The cut is not free and the hold is not free.
Leverage decides urgency. Sellers carrying debt should reprice decisively. Sellers who own outright should usually fix the listing before they touch the price.
Insurance is now an underwriting question for buyers. The South Carolina Wind and Hail Underwriting Association's 8% dwelling increase took effect in February 2026 — have your declarations ready.
What Sullivan's Island Sellers Are Actually Experiencing
Two markets are running at once in Charleston, and they are not behaving the same way.
The regional market is functioning. Across the Charleston Trident footprint in August 2026, closed sales rose 2.5% year over year, pending sales rose 11.8%, and sellers collected 95.8% of original list price at a 51-day median — with 3.6 months of supply, per CTAR/ShowingTime as of August 2026. That is a normal, liquid market.
The top of the barrier-island market is not. Sullivan's Island recorded 7 closed sales in August 2026, down 20.2% year over year, at a $3,597,619 median — down 17.3% — with sale-to-list at 95.5%, off 2.3 points, per Redfin as of August 2026. Treat that median with caution: at seven transactions, the mix of what sold moves the number more than values do.
The signal worth acting on is not the median. It is the 147 days, and the 56-day deterioration behind it.
Citation & Key Stat
At a 147-day median versus 51 days for the Charleston Trident region, a Sullivan's Island home now takes2.9 times as long to sell as the average listing in the metro. That is a time problem, not a price problem — and the two carry very different remedies.
Ratio calculated from Redfin's Sullivan's Island median days on market of 147 and the Charleston Trident Association of Realtors / ShowingTime regional figure of 51, both as of August 2026.
Why the rate move matters in a cash-heavy market
The standard objection: Sullivan's Island buyers pay cash, so who cares about rates? Partly true — all-cash purchases were 31.4% of U.S. sales in the first four months of 2026 per a Realtor.com analysis, and the share runs far higher at this price point. But rates reach you through two doors.
Jumbo pricing follows the long end of the curve, and the 10-year Treasury topped 5.3% in early October (per Bankrate, October 2026), so financed buyers at $3M+ are requalifying downward in real time. More important for a cash buyer: that 5.3% risk-free yield is now the competition. A second home is being measured against a Treasury that pays without a roof, a dock, or a wind-and-hail renewal.
The Carry-vs-Concession Test
Most sellers compare a proposed reduction to their original asking price. That is the wrong comparison. The right one is the reduction against the cost of the time it buys you. Three steps.
Step 1 — Price your true monthly carry
Five monthly lines: debt service if any; property taxes (South Carolina assesses non-primary residences at 6% rather than the 4% owner-occupied ratio, so pull your actual bill); wind-and-hail plus flood premiums from your current declarations; maintenance, utilities, and grounds; and the line most sellers omit — opportunity cost on your trapped net equity at today's yields.
Step 2 — Price the time you are actually buying
Multiply monthly carry by five, using the 147-day median as your planning figure. Then remember it is a median: half of Sullivan's Island sellers waited longer. If a seven-month hold would strain you, that is your answer before you reach step three.
Step 3 — Find your indifference figure, then choose the lever
Compare the five-month carry to the concession. On a $3.6M listing owned outright — illustratively, $3.3M net at a 5.3% opportunity cost plus roughly $4,500 a month in taxes, insurance, and upkeep — carry runs near $19,000 a month, about $95,000 over five months. A 3% cut is $108,000. In practical terms, the same number. Substitute your own figures; these assumptions are illustrative.
LeverApproximate costWhen it is the right callCut the price 3%~$108,000Price is the verified objection in showing feedbackHold and carry five months~$95,000No debt service, and the listing is genuinely well presentedReinvest a fraction, keep the rest$15,000–$30,000Price is not the objection — the usual case at 147 days
Here is the part that is not obvious: when a cut and a five-month hold cost about the same, the cut stops being the default and becomes one of three ways to spend the same hundred thousand dollars. The third option wins whenever price is not the real objection — and at 147 days, it usually is not.
What To Do in the Next 30 Days
Put the insurance file in the listing. Elevation certificate, flood zone, current wind-and-hail and flood declarations, any mitigation credits. With the SCWHUA increase effective February 2026, buyers at this level underwrite your premium before your price. Answering that at the first showing removes weeks.
Audit the feedback for the actual objection. Ten showings with no offer is data. If nobody has mentioned price, a reduction buys nothing but a weaker negotiating position.
Reshoot if the photography is off-season. A listing shot in February that is still live in October reads as stale before a buyer processes a single detail.
Offer a rate buydown credit instead of a cut where the buyer is financed. At 7.5%, a concession applied to points moves a monthly payment further than the same dollars off the price. Structure it with your lender; the arithmetic is loan-specific.
If you reprice, do it once and decisively. Three small reductions train the market to wait for the fourth. One meaningful move resets the listing.
Local Market Context: Sullivan's Island Against the Rest of Charleston
Metric, August 2026Sullivan's IslandCharleston Trident regionMedian sale price$3,597,619$431,500Median days on market14751Sale-to-list / % of original list95.5%95.8%Closed sales, year over year−20.2%+2.5%
Sullivan's Island figures per Redfin; regional figures per CTAR/ShowingTime, both as of August 2026. The series are compiled differently and seven sales make the island median volatile — read as context, not like-for-like.
Notice that percent of list held almost exactly in line with the region. Sullivan's Island sellers are not being forced into deep discounts. They are waiting. That distinction is the whole argument for treating this as a time problem.
The structural case underneath is a supply story. The island is effectively built out, with a Design Review Board governing what gets built, so inventory depends on who decides to list — not who decides to build. No new-construction pipeline is arriving to compete with you, which a Mount Pleasant or Berkeley County seller cannot say.
Replacement cost reinforces it. Anything new here must clear current elevation requirements, coastal wind code, stormwater and tree protection review — putting build cost per square foot materially above comparable mainland work before a single finish selection. When medians wobble on seven sales, land value and replacement cost hold the floor.
Frequently Asked Questions
How long does it take to sell a house on Sullivan's Island?
The median was 147 days in August 2026, per Redfin — up 56 days from a year earlier. Plan for five months and have a contingency for seven. Half of all sellers took longer than the median.
Should I reduce my price or wait out the market?
Run the carry-vs-concession test above. With no debt, five months of carry and a 3% cut cost roughly the same, so reduce only if price is the objection buyers are actually raising. With debt service, your carry is cash out the door rather than opportunity cost, and repricing sooner is usually the better risk decision.
Do mortgage rates matter if Sullivan's Island buyers pay cash?
Yes, through two channels. Jumbo financing tracks the 10-year Treasury, which topped 5.3% in early October 2026 per Bankrate. And a 5.3% risk-free yield is itself the competing investment for a cash second-home buyer.
Will rising insurance costs hurt my sale price?
They are more likely to slow your sale than cut your price. The SCWHUA's 8% dwelling increase took effect February 2026, so buyers are quoting higher premiums than last year's comparables assumed. Supplying the elevation certificate, declarations, and mitigation credits up front shortens diligence substantially. Confirm specifics with a licensed coastal insurance agent.
Is this a bad time to list on Sullivan's Island?
Slow, not weak. Sellers held 95.5% of list, in line with the region's 95.8%. This market's cost is measured in months, not discounts — so listing is a question of whether you can carry the timeline.
What does a price reduction signal to buyers at this level?
That more may follow. One decisive reduction reads as a repositioned listing. A sequence of small ones reads as a seller discovering their price in public, and buyers price that discovery into their offer.
Looking to buy, build, or invest in Charleston real estate? I'm Chris Eller, Broker Associate with The Cassina Group and a luxury real estate developer specializing in new construction and coastal properties across Charleston and the barrier islands.
Call or text: 843-343-3359 | Email: Chris@TheCassinaGroup.com | ChrisEllerRealEstate.com
If you're considering buying, selling, or building in Charleston or anywhere in the Lowcountry, reach out anytime for expert guidance.
