Charleston's Luxury Buyers Have More Homes to Choose From — and Less Time to Decide
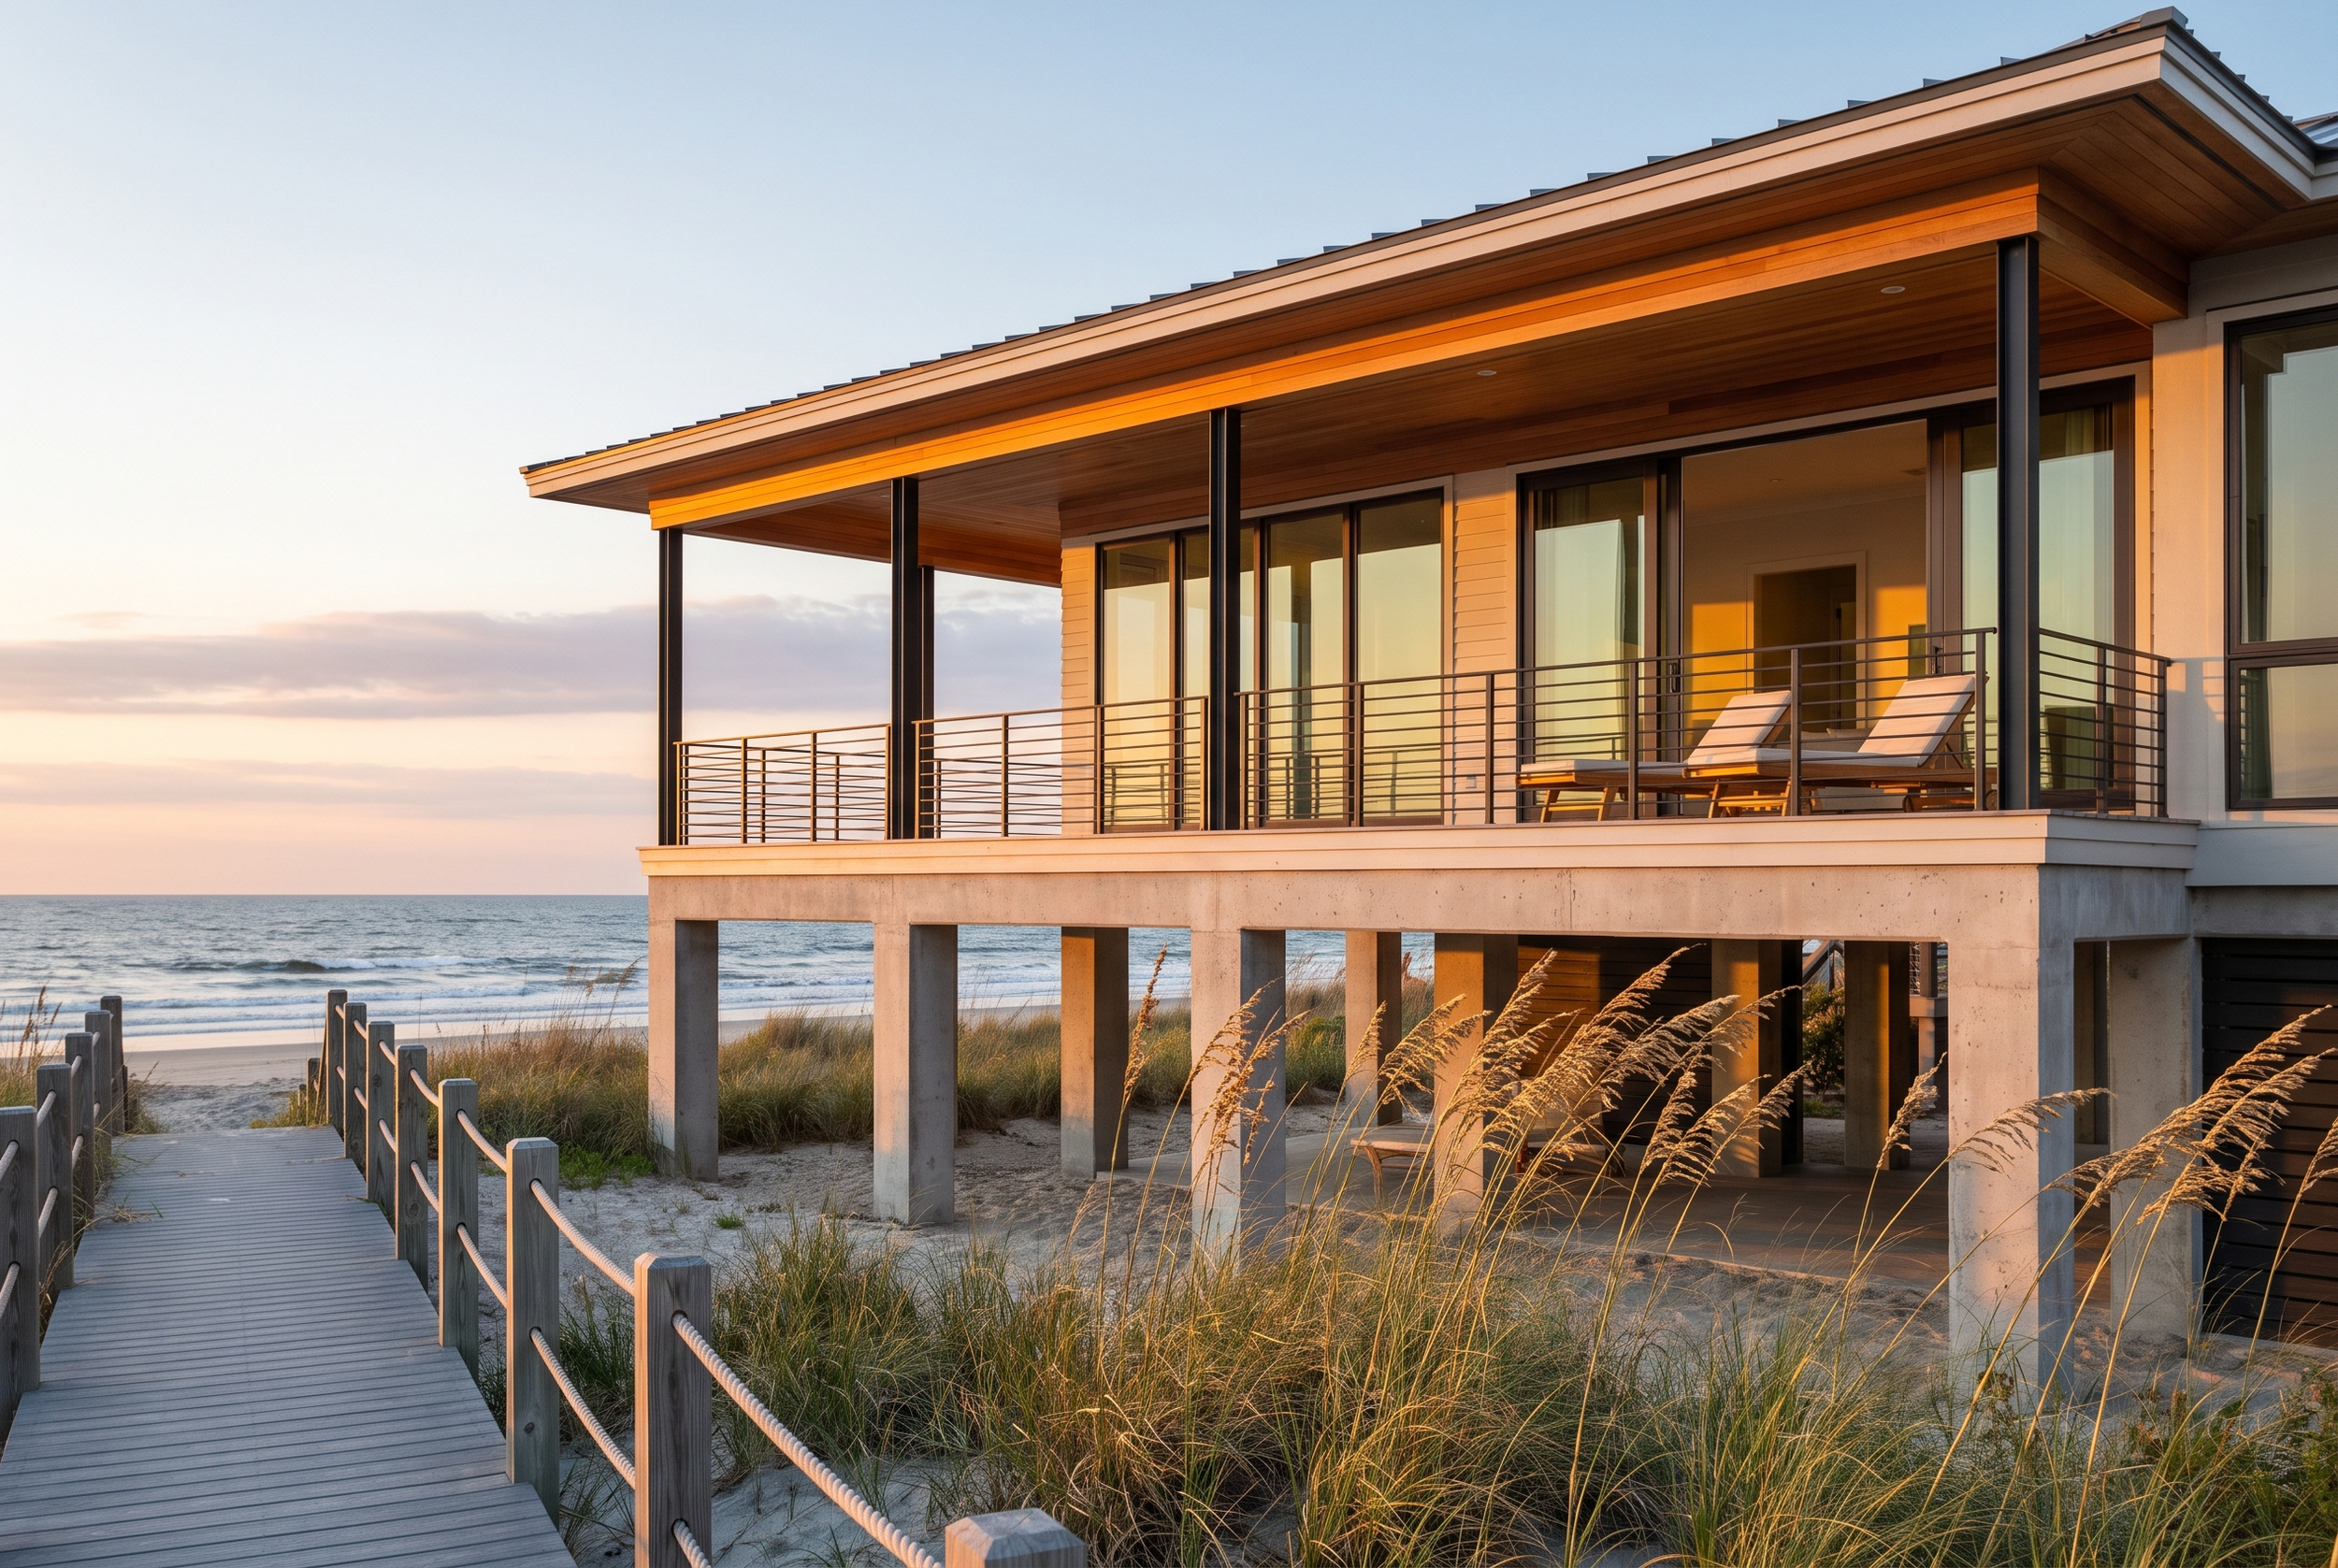
If you are shopping above $1 million in Charleston this fall, the honest answer to the question everyone is asking — has the luxury market finally turned in my favor? — is: only halfway. There are more $1 million-plus homes on the market across the Charleston Trident region than there were a year ago, but the region is absorbing them faster than it did a year ago. More choice, less dwell time. That combination is the opposite of what the mid-market is doing, and it is why a buyer who waits out a listing on Isle of Palms this fall is playing a different game than a buyer waiting one out in Summerville.
Key Takeaways
$1M+ inventory is up 4.6% year over year (837 homes), but months supply in that tier fell 9.5% to 3.8 months — per CTAR/ShowingTime Housing Supply Overview, August 2026.
The $1M+ band is the only tier where listings grew meaningfully and absorption improved meaningfully at the same time.
Region-wide, the picture is softer: 51 days on market (+6.3%) and 95.8% of original list price received, per CTAR, August 2026.
Rates moved against buyers this month — 6.95% on the 30-year fixed as of September 17, 2026, up from 6.76% the prior week and 6.26% a year ago (Freddie Mac PMMS).
Practical read: negotiate hard on price-corrected and dated luxury listings; move quickly on correctly priced waterfront and new construction, where depth of supply is thin.
What the August Numbers Actually Say
Start with the region, because it frames everything else. Charleston Trident closed 1,614 sales in August 2026, up 2.5% year over year, at a median price of $431,500 — a 1.8% gain. New listings fell 4.6%. Days on market rose to 51, and sellers collected 95.8% of original list price (CTAR/ShowingTime Local Market Update, August 2026). That is a market with modest price growth, longer marketing times, and fewer sellers willing to test it.
Now split it by price. The tier data tells a different story at the top:
Price RangeInventory (Aug 2026)Inventory YoYMonths SupplyMonths Supply YoY$1,000,001 and above837+4.6%3.8−9.5%$750,001–$1,000,000383−9.0%3.1−18.4%$500,001–$750,0001,025+8.5%3.60.0%$350,001–$500,0001,652+5.4%3.50.0%
Source: CTAR/ShowingTime Housing Supply Overview, August 2026.
Look at the middle two rows. The $500K–$750K band added 8.5% more listings and months supply did not move at all — the extra inventory simply lengthened the queue. That is real buyer leverage. The $1M+ band added inventory too, and months supply dropped. Same headline, opposite meaning.
The Absorption Gap Test: Reading Leverage in Three Steps
Most buyers stop at one number — "inventory is up" — and assume leverage follows. It often does not. Here is the three-step check I run before setting an offer strategy in a specific price band. Call it the Absorption Gap Test.
Step 1 — Pull the tier, not the market
Region-wide figures blend a $350,000 Goose Creek ranch with a $4 million Sullivan's Island lot. They are not the same market and are not moving the same direction. Pull inventory and months supply for your actual price band.
Step 2 — Put the two year-over-year changes side by side
Inventory change tells you how much more there is to choose from. Months supply change tells you how fast it is leaving. One without the other is half a picture.
Step 3 — Read the gap
Inventory up and months supply flat or up means supply is outrunning demand: negotiate on price, ask for closing costs, take your time. Inventory up and months supply down means demand grew faster than supply: negotiate on terms and condition, not headline price, and expect competition on the best properties. That second case is Charleston's $1 million-plus market today.
Citation & Key Stat
"Charleston's $1 million-plus segment is now clearing roughly 220 homes a month, up from about 190 a year ago — a 16% gain in absorption — over the same twelve months in which the average 30-year fixed mortgage rate rose from 6.26% to 6.95%."
Absorption figures calculated by Chris Eller from inventory (837, +4.6%) and months supply (3.8, −9.5%) reported in the CTAR/ShowingTime Housing Supply Overview, August 2026. Mortgage rates per Freddie Mac Primary Mortgage Market Survey, September 17, 2026.
The rate detail matters because it isolates the buyer. When financing gets 69 basis points more expensive and the top of the market speeds up anyway, you are looking at demand that is not rate-driven. That is the equity buyer, the relocation buyer, and the second-home buyer — and none of them are waiting on the Fed.
Buyer Strategy for the Next 90 Days
Separate dated listings from priced listings. With 837 homes above $1 million on the market, a meaningful share have been sitting since spring. Those are your negotiation candidates — and with regional days on market at 51 and rising, a 90-plus-day luxury listing is genuinely stale. A fresh, correctly priced oceanfront or marsh-front listing is not.
Do not lead with a low number on thin supply. True oceanfront on Isle of Palms and Sullivan's Island is a handful of properties at any moment. On those, win on certainty: shorter due diligence, proof of funds up front, a rent-back if the seller needs one. Save the price fight for the properties with comparable alternatives.
Underwrite insurance before you underwrite the mortgage. Windstorm and flood premiums on barrier-island property have become a material line item, not a rounding error, and they vary enormously by elevation certificate, roof age, and wind mitigation features. Get a bindable quote during due diligence, not after. An older, low-elevation house can carry a carrying cost that reprices the whole deal.
Price the renovation at today's cost, not 2021's. Elevated construction, impact glass, and current wind-code framing are expensive, and permitting timelines in Charleston County and the barrier-island towns are not fast. If your offer assumes a renovation, get a builder's number before you go firm.
Seller Strategy: The First Three Weeks Decide It
Sellers above $1 million are in a better position than the regional headlines suggest — but only on entry. At 95.8% of original list price region-wide, the market is paying close to ask for correctly priced homes and punishing the rest. Overprice by 10% in September and you will spend October and November chasing the market down, and your eventual buyer will use your days-on-market count against you.
Two things move the needle here: photography and elevation of finish. Buyers at $2 million are comparing your house against new construction with impact glass, current code, and a warranty. If your home is fifteen years old, either invest in the two or three visible updates that close the gap, or price against that competition from day one. Hoping nobody notices costs more than either.
Isle of Palms and the Barrier-Island Context
The absorption story has a local shape. Isle of Palms closed 2025 with 16 December sales, up 45.5% year over year, at average prices up 38.4% to $2.3 million, and the island's current high-water mark is a 4,514-square-foot oceanfront home at 1 44th Avenue asking $18 million — against a previous island record of $14.2 million set in April 2025 (The Post and Courier). The ceiling is being tested, and that pulls the whole island up with it.
Supply on the islands is constrained by something county-wide statistics cannot capture: you cannot make more of it. Between critical-area setbacks, OCRM jurisdiction, wetlands, stormwater requirements, and tree protection, the buildable lot inventory on Isle of Palms and Sullivan's Island is effectively fixed. New construction that does come online carries the full cost of elevated foundations, current wind code, and a permitting timeline measured in quarters. That is why teardown-and-rebuild economics increasingly set the floor under older island housing stock — a dated house on a good lot is priced off replacement cost, not off its own condition.
Mount Pleasant and Daniel Island behave differently. Both have more depth of $1M–$2M inventory, more new construction in the pipeline, and therefore more genuine negotiating room on a dated listing than the islands do. Run the Absorption Gap Test submarket by submarket before you assume otherwise.
Frequently Asked Questions
Is now a good time to buy a luxury home in Charleston?
For a buyer with a specific target, yes — selection above $1 million is the widest it has been in several years. But the segment is absorbing homes about 16% faster than a year ago, so "wide selection" is not the same as "no urgency."
Are Charleston home prices falling in 2026?
No. The regional median rose 1.8% year over year to $431,500 in August 2026. What has changed is speed: days on market rose to 51, and fewer homes are selling above asking.
How much are mortgage rates right now?
The 30-year fixed averaged 6.95% for the week of September 17, 2026, up from 6.76% the week before and 6.26% a year earlier, per Freddie Mac. Rate quotes vary by lender, credit profile, and property type — talk to a licensed lender for terms specific to you.
Is it cheaper to buy or build on Isle of Palms?
It depends on the lot. Once you add elevated foundation work, current wind-code framing, impact glazing, stormwater compliance, and a multi-quarter permitting timeline, building is rarely the cheaper path on a barrier island — but it can be the better path when the alternative is a dated house that needs a gut renovation anyway. Price both before you commit.
How long should a $2 million Charleston listing take to sell?
At 3.8 months of supply in the $1M+ tier, a correctly priced home should attract serious activity inside the first three weeks. If it has not after 45 days, the issue is price or presentation, not the market.
Do I need flood insurance on Isle of Palms or Sullivan's Island?
Most barrier-island properties sit in a mapped flood zone, and lenders require coverage there. Premiums vary widely with elevation certificate, foundation type, and construction date. Get a bindable quote during due diligence rather than relying on the seller's current premium.
Let's Talk About Your Next Move
Looking to buy, build, or invest in Charleston real estate? I'm Chris Eller, Broker Associate with The Cassina Group and a luxury real estate developer specializing in new construction and coastal properties across Charleston and the barrier islands.
Call or text: 843-343-3359
Email: Chris@TheCassinaGroup.com
Website: ChrisEllerRealEstate.com
If you're considering buying, selling, or building in Charleston or anywhere in the Lowcountry, reach out anytime for expert guidance.
