Selling a Home on James Island? The First 21 Days Now Decide What You Net
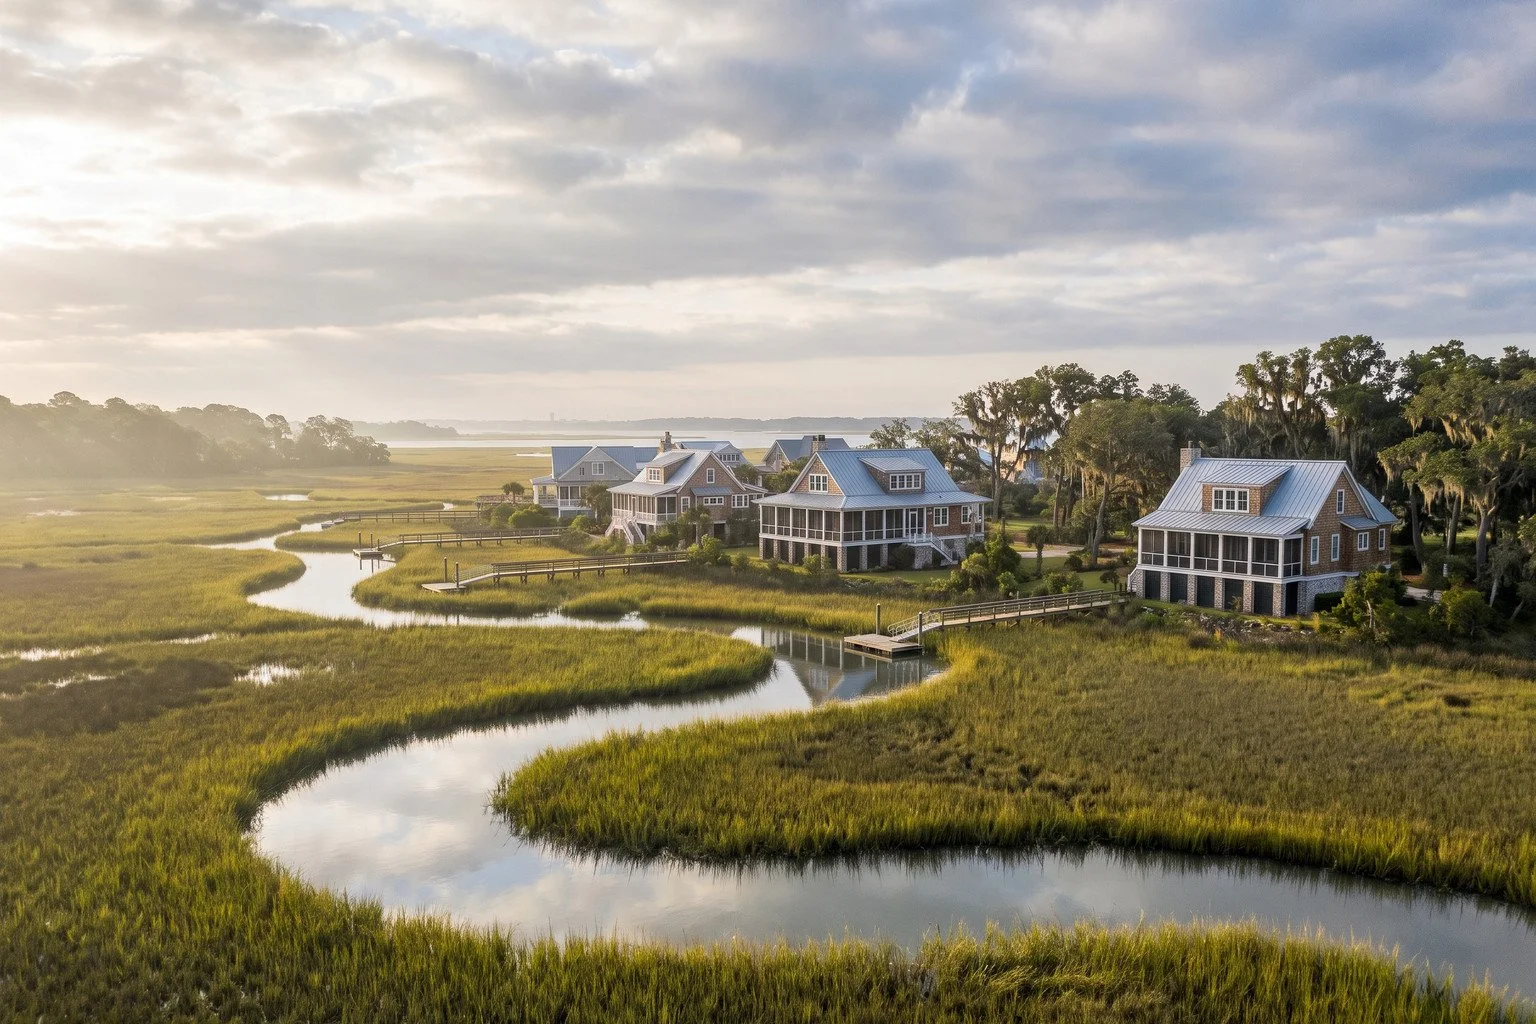
If you are selling a home on James Island this fall, the single most important decision you make is the number you put on it the day it goes live. Charleston County single-family sellers closed August 2026 at 95.4% of their original list price, and average days on market rose 11.6% year over year to 43 days, per the Charleston Trident Association of REALTORS® Local Market Update, August 2026. The market is still transacting. It is simply no longer forgiving an aspirational first number. Price it to the last 90 days of closed comparables and you sell near ask. Price it to what the neighbor is asking and you will very likely fund the difference out of your own proceeds.
Key Takeaways
Charleston County single-family homes closed at 95.4% of original list price in August 2026, down 0.5 points year over year (CTAR, Aug 2026).
Average days on market rose 11.6% to 43 days in Charleston County; the Trident-wide figure is 51 days, up 6.3%.
Inventory is not the problem. Trident months supply sits at 3.6 months, down 2.7% year over year. Pricing is the problem.
The 30-year fixed averaged 6.76% on September 10, 2026, up from 6.71% the prior week and 6.35% a year ago (Freddie Mac PMMS).
Nationally, 26.3% of listings took a price cut in August (Zillow) — a reduction is now ordinary, but a second reduction is what costs money.
Act on data, not on drive-by asking prices. Use the three-step ladder below before you set your number.
What the August 2026 Numbers Actually Say About Charleston Sellers
Read the Charleston data in the right order and the story is clear. Demand has not collapsed — Trident-wide closed sales rose 2.5% year over year in August 2026 to 1,614. Supply has not flooded either: new listings fell 4.6% to 2,066 and months supply tightened to 3.6 months (CTAR, August 2026). What changed is the pace and the terms.
Charleston County single-family detached is where the pressure shows. Median sale price slipped 0.5% to $770,500 while the average dropped 7.5% to $1,194,910 — a gap that says the upper end is trading thinner, not that values broadly fell. Days on market climbed 11.6%; percent of original list price received fell to 95.4%.
Now the national picture. Zillow's August 2026 report has the typical U.S. home going pending in 27 days, unchanged from a year earlier, with 26.3% of listings taking a price cut. Charleston County single-family listings are averaging 43. Even allowing that Zillow reports a median days-to-pending and CTAR an average days-on-market — not a like-for-like measure — the direction is unambiguous: our single-family segment is slowing while the national number holds flat.
For a James Island seller, that is the headline. You are not in a market where a pricing mistake gets bailed out by the next wave of buyers. You are in one where it gets absorbed by your own equity.
The Lowcountry Pricing Ladder: Three Rungs Before You List
Most pricing advice tells sellers to "be realistic." That is not a method. Here is the one I use with sellers across James Island, Mount Pleasant, and the barrier islands. Three rungs, climbed in order.
Rung One — Price to closed comps, never to active asks
Active listings tell you what your neighbors hope to get. Closed sales from the last 90 days tell you what buyers and appraisers agreed to. On James Island, where a 1960s ranch and a new elevated build can sit on the same street, pull comps by structure type and elevation — not by zip code. Adjust for what Lowcountry buyers underwrite in 2026: finished floor elevation relative to base flood elevation, roof age, whether mechanicals sit above the flood plain, and whether the flood policy is assumable.
Rung Two — Run the 14-Day Showing Test
Your listing tells you the truth within two weeks. Showing volume measures whether your price cleared the search filter. Second showings and offers measure whether the property held up once buyers walked it — two different failures with two different fixes.
First 14 days on marketWhat it meansAction8+ showings, 2+ second showings, an offerPriced correctlyHold. Negotiate terms, not price.8+ showings, no second showings, no offerPrice cleared the filter; the product did notFix condition, photography, or staging. A cut alone will not solve it.3–7 showings, no offerPriced at the top of the bandOne correction, timed to day 21.Fewer than 3 showingsPriced outside the marketMaterial correction now. Do not wait 60 days.
Rung Three — Make one decisive correction, not a series of trims
This is where Charleston sellers lose real money. A $15,000 trim on a $900,000 James Island listing is a rounding error to a buyer and a signal of weakness to their agent. Worse, it rarely moves you across a search-filter boundary, so the same buyer pool sees the same listing at a slightly lower number.
Correct once, correct below the nearest round threshold ($899,000 to $849,000, not $885,000), and correct by day 21 to 30 while the listing is still fresh. The part most sellers miss: the cost of a correctly sized first reduction is almost always less than the carrying cost plus the second reduction you will make anyway 60 days later. With the 30-year fixed at 6.76% as of September 10, 2026 (Freddie Mac PMMS), the buyer pool renews slowly. Time is not on the seller's side the way it was in 2021.
Citation & Key Stat
"Charleston County single-family sellers closed August 2026 at 95.4% of original list price on a $770,500 median — roughly a $35,400 gap between the first number a seller asks and the last number they sign."
Calculated from Charleston Trident Association of REALTORS® Local Market Update, August 2026: median sales price $770,500 and percent of original list price received 95.4%. Analysis by Chris Eller, Broker Associate, The Cassina Group.
What James Island Sellers Should Do Between Now and the Holidays
Three practical moves for the next 90 days.
1. List now rather than in January. New listings fell 4.6% Trident-wide in August and the fall pipeline is thin. Less competition partly offsets the seasonal dip in traffic, and buyers still shopping in October are not browsing — they are under a deadline.
2. Pre-underwrite your own house. Order the elevation certificate, pull the flood policy and its renewal number, inspect the roof, and put it all in the listing file before a buyer's inspector finds it. In coastal Charleston, insurance is a financing issue now, not a closing formality — a buyer who cannot get a bindable quote cannot close, and you will have burned 30 days finding out.
3. Budget a concession instead of a second price cut. A rate buydown often buys more monthly payment relief per dollar than an equivalent reduction, and it keeps your closed price — and your neighborhood's comps — intact. Run both scenarios before agreeing to either; your lender should model the specifics.
James Island in Context: Elevation, Insurance, and the New Construction Pipeline
James Island sits minutes from downtown and from Folly Beach, with stock running from mid-century ranches to marsh-front custom builds. That range is why island-wide averages mislead. A slab-on-grade ranch in a flood zone and an elevated new build three streets over are not in the same buyer conversation and should never be comped against each other.
The construction side reinforces the pricing discipline. Replacement cost here is set by elevated foundations, wind-rated envelopes, stormwater detention, and tree protection — none of which get cheaper. That puts a floor under quality inventory even in a slower market, and it explains the average-versus-median spread in the county data: buyers are paying for elevation and code compliance and discounting deferred maintenance harder than they did two years ago.
If your home is elevated, recently re-roofed, and insurable at a reasonable premium, you have a scarce product — hold your number. If it is not, price for the work the buyer is about to inherit, because their lender and carrier will price it for them either way.
Frequently Asked Questions
Is now a good time to sell a home on James Island?
Yes, with a caveat. Trident-wide closed sales rose 2.5% year over year in August 2026 and months supply sits at 3.6 months (CTAR), so buyers are transacting. But days on market rose and Charleston County sellers are netting 95.4% of original list. Correctly priced homes sell; optimistically priced homes sit.
How long does it take to sell a house in Charleston right now?
Average days on market until sale was 43 days in Charleston County and 51 days Trident-wide in August 2026 (CTAR), both up year over year. Add roughly 30 to 45 days from contract to closing for a financed buyer.
Should I reduce my price or offer a concession?
Run both. A seller-paid rate buydown often delivers more monthly payment relief per dollar than the equivalent price cut, and it preserves your closed sale price. A reduction is the right tool when showing volume says you never cleared the search filter. Ask your lender to model your price point.
How much do mortgage rates affect what I can get for my James Island home?
Directly, through the buyer's qualifying payment. The 30-year fixed averaged 6.76% the week of September 10, 2026, up from 6.35% a year earlier (Freddie Mac PMMS). Higher rates shrink the pool at every band, which is why the size and timing of your first correction matters more than it did in a 4% market.
Do flood zone and elevation change my list price on James Island?
They change what a buyer can finance and insure, which sets your ceiling. Two structurally similar homes can carry very different annual insurance costs based on finished floor elevation and flood zone. Get the elevation certificate and a current quote before you price, not after you are under contract.
What should I do before my home goes live?
Pull 90-day closed comps by structure type and elevation, order the elevation certificate, confirm insurability, clear visible deferred maintenance, and set a written day-21 trigger based on showing volume. Decide the correction in advance, before emotion is in the room.
Thinking About Selling, Building, or Investing in Charleston?
I'm Chris Eller, Broker Associate with The Cassina Group and a luxury real estate developer specializing in new construction and coastal properties across Charleston and the barrier islands.
Call or text: 843-343-3359
Email: Chris@TheCassinaGroup.com
Website: ChrisEllerRealEstate.com
If you're considering buying, selling, or building in Charleston or anywhere in the Lowcountry, reach out anytime for expert guidance.
